Wind Mitigation Insurance Discounts and Impact Windows in Florida
Wind mitigation insurance discounts are credits Florida law requires home insurers to offer for documented features that reduce wind damage, including opening protection. They are recorded on Form OIR-B1-1802, revised effective April 1, 2026 and valid up to five years. For the opening protection credit, generally every glazed opening must be protected.
What Does Florida Law Require Insurers to Offer?
Section 627.0629, Florida Statutes, requires residential property insurance rate filings to include actuarially reasonable discounts, credits, or other rate differentials for construction features shown to reduce windstorm losses. The statute names roof strength, roof covering performance, roof-to-wall strength, opening protection, and window, door, and skylight strength.
Section 627.711 requires insurers to notify policyholders of available mitigation discounts at issuance and each renewal, and since October 1, 2023, to describe them on their websites.
Wind mitigation insurance discounts depend on your insurer, home, and policy. The wind portion of a Florida premium is often a large share of the total, and opening protection can reduce it, but no one can promise a specific amount. Ask your agent to run the numbers with your current report.
What Is Form OIR-B1-1802?
The Uniform Mitigation Verification Inspection Form, the “wind mit” or “1802,” is the state form insurers use to apply wind mitigation insurance discounts. The Florida Office of Insurance Regulation (OIR) adopted OIR-B1-1802 (Rev. 04/26), effective April 1, 2026, based on a 2024 wind-loss mitigation study.
Validity
Up to five years, as long as the structure has no material changes and no inaccuracies are found.
Older forms
Citizens Property Insurance Corporation said it would keep accepting the prior version (Rev. 01/12) if completed within five years before April 1, 2026 and the structure has not changed. Ask your own insurer about its rules.
Keep a copy
With your insurance policy documents, as the form instructs.
What Does the Form Check?
The April 2026 revision adds items including a design wind speed region, roof slope, and FORTIFIED Home designations. Citizens noted these additions did not change its credits at this time.
The form evaluates seven core features:
Building code
The code the home was built under, by permit date.
Roof covering
Type and code compliance, by permit date or product approval.
Roof deck attachment
How sheathing is nailed to trusses or rafters.
Roof-to-wall attachment
Toe nails, clips, single wraps, or double wraps.
Roof geometry
Hip, flat, or other shapes.
Secondary water resistance
A sealed roof deck.
Opening protection
The weakest level of wind-borne debris protection on any opening.
How Does the Opening Protection Credit Work?
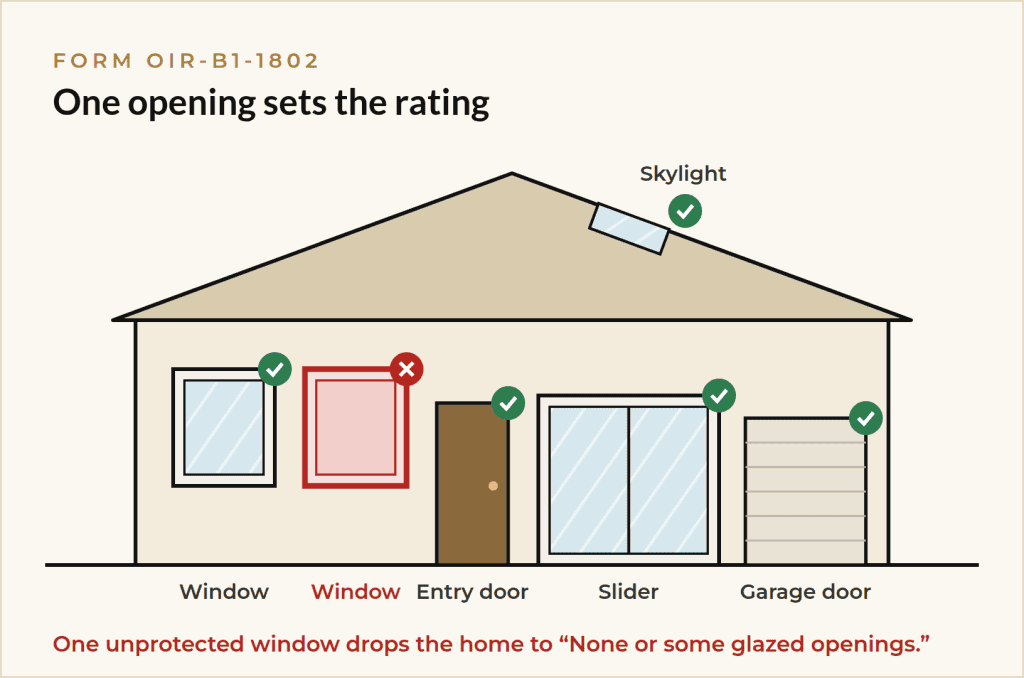
Opening protection covers windows, entry doors, sliding glass doors, skylights, and garage doors (not gable or roof vents). The inspector records the weakest protection found, and that one opening sets the rating for the whole home.
Non-glazed openings, such as solid entry doors and garage doors without glass, affect the sub-rating (A.1 versus A.3, for example). The MSFH Homeowner’s Guide advises asking your insurer which A rating your discount needs.
All glazed openings must be protected
With approved impact products or approved shutters to reach the top ratings. Level A requires products tested to large missile impact and cyclic pressure standards (Florida Building Code TAS 201, 202, and 203, ASTM E1886 and E1996, or Miami-Dade protocols) and listed in the Florida or Miami-Dade approval system.
One unprotected window can drop the whole rating
To "None or some glazed openings."
Unverified products count less
Protection that looks impact rated but has no documentation is classified lower.
Damaged openings can disqualify the home
The form states buildings with openings needing replacement do not qualify for rate differentials.
Window film and decorative shutters do not count
Hurricane window film and decorative or non-rated shutters are not approved opening protection, so they do not earn the credit.
How Impact Windows and Doors Earn Wind Mitigation Insurance Discounts
Replacing every window and exterior door with approved impact products is one of the most direct ways to reach the top opening protection category, because protection is always in place. Common gaps we see:
- A garage door or rear French door that was never upgraded.
- A small bathroom or transom window left out of a partial project.
- Skylights with no impact rating.
Storm Pro Window and Door quotes every opening on the home so nothing is missed, and a Florida-licensed crew (CRC1334277) installs and permits the work. If you are phasing, plan the last phase to finish the whole home, then schedule a new inspection. See our impact windows, impact doors, and impact sliding glass doors.
Documentation to Keep
An inspector can only credit what can be verified, so keep:
- Florida Product Approval or Miami-Dade NOA numbers for every window, door, garage door, and skylight (how to look them up).
- Building permits and final inspection records (impact window permits guide).
- Installation dates and the contractor's invoice listing each opening.
- Photos of product labels, glass etching, and each installed opening.
- Your current and prior OIR-B1-1802 forms.
Storm Pro provides the approval number for every opening and closes the permit, so this folder is complete when the job is done.
How to Get a Wind Mitigation Inspection
My Safe Florida Home participants receive a program inspection at no cost, and grant recipients receive a final inspection after their project.
This page is general information, not insurance or legal advice. Discounts are set by each insurer under rates reviewed by OIR.
Wait until all work is finished
And the permit is closed.
Hire a qualified inspector
Section 627.711 lists who may sign the form, including licensed home inspectors with hurricane mitigation training, certified building code inspectors, licensed general, building, or residential contractors, professional engineers, and architects.
Gather your documentation
Before the visit.
Review the form
For accuracy, especially opening protection.
Send it to your agent or carrier
And ask how your premium changes.
Official Sources
Every rule, number and deadline on this page comes from the agencies below. Check them directly anytime.
01
02
03
Citizens Property Insurance Corporation
citizensfla.com ↗
04
05
06
Frequently Asked Questions
How much can impact windows save on insurance in Florida?
It varies by insurer, home, location, and policy, so no one can give a fixed number in advance. Florida law requires insurers to offer credits for documented opening protection. Get a wind mitigation inspection after installation and ask your agent to quote your premium with the new form.
Do I have to replace every window to get the opening protection discount?
Generally, yes. The form rates the weakest protection on any glazed opening, including windows, doors, sliders, skylights, and garage doors with glass. If one glazed opening is unprotected, the home is rated as having no or partial protection, which usually means little or no opening protection credit.
How long is a wind mitigation report good for?
Up to five years, provided the structure has no material changes and no inaccuracies are found. Replacing windows and doors is a change worth documenting with a new inspection so your insurer sees the upgrade. Keep the old and new forms together with your policy documents.
What changed on the 2026 wind mitigation form?
OIR adopted OIR-B1-1802 (Rev. 04/26), effective April 1, 2026. It adds a design wind speed region, roof slope, and FORTIFIED Home designations, and updates roof and opening categories. Citizens said the additions did not change its credits at this time. Ask your insurer whether it accepts older forms.
Does hurricane window film count for wind mitigation insurance discounts?
No. Window film is not an approved impact-resistant product for opening protection. The top levels require products tested to large missile impact and cyclic pressure standards and listed in the Florida or Miami-Dade approval system. A home relying on film is generally rated as unprotected on those openings.
Who can do a wind mitigation inspection in Florida?
Section 627.711 lists licensed home inspectors with hurricane mitigation training, certified building code inspectors, licensed general, building, or residential contractors, professional engineers, and licensed architects. Verify the inspector’s license at myfloridalicense.com before the visit, and have your product approvals and permits ready so every opening can be credited.